

This was the question being asked about a small block of flats owned by a client of ours, triggered by changes announced in the tax laws.
Either way, on the numbers, the return was the same – single digits only. What would move the needle here, I wondered? Redeveloping the block, if handled right, looked on paper like a triple figure result.
In finance, there’s no free lunch. Would the risk be worth it? That was the job at hand.
Doesn’t sound like an intro to a James Bond episode, granted, but stay with me.
Going through the trust’s tax return and financial statements, pulling the numbers I needed for the “hold” case, I noticed the insurance costs were missing. Who cares, right? I wasn’t auditing insurance right then, I was pricing a small subdivision.
A $20m oversight?
So I went to the property folder and sure enough, the strata policy schedule was sitting right there, filed and correct-looking. Except the expiry date on it was a month before the client had come on board with us.
The policy had lapsed before he was ever a client of ours — and it had simply stayed that way, unnoticed by everyone whose job touched it since.
Somebody should have asked why. And on our watch, we do.
I rang the accountant. One year’s return, and no insurance premium in it.
Her answer took four seconds. “He seems pretty organised — maybe he’s just paying it from a personal account.” She’d already noted the blank in her working papers: worth asking again next year, she said, so she could amend the return if it turned out he’d simply paid it another way.
Reasonable. Also wrong, as it turned out. But there was no urgency in it from where she sat — a question parked for next year’s return, not anyone’s emergency. That’s what a well-run file looks like from her chair: a plausible gap, noted, deferred.
Which is the part that should worry you more than a mistake would. Nobody had been careless. And the building had gone a full year with nothing standing behind it at all.
A potential ‘game over’ moment
This wasn’t an administrative nuisance. This was potentially game over.
There’s a reason a strata policy carries $20 million in public liability, not $2 million. A landing falls into disrepair, a toddler goes down the stairs, and a child who should have had an ordinary life instead needs full-time care for the next eighty years. That’s not a rare hypothetical. It’s exactly the scenario the $20 million exists for.
My client is worth somewhere between $10 and $15 million. A $20 million statement of demand from the Court is enough to sink my client’s ship — and it takes years alongside it, litigation run personally rather than handed to an insurer to fight, the kind of grind that wears down marriages and health long before it finishes with the money.
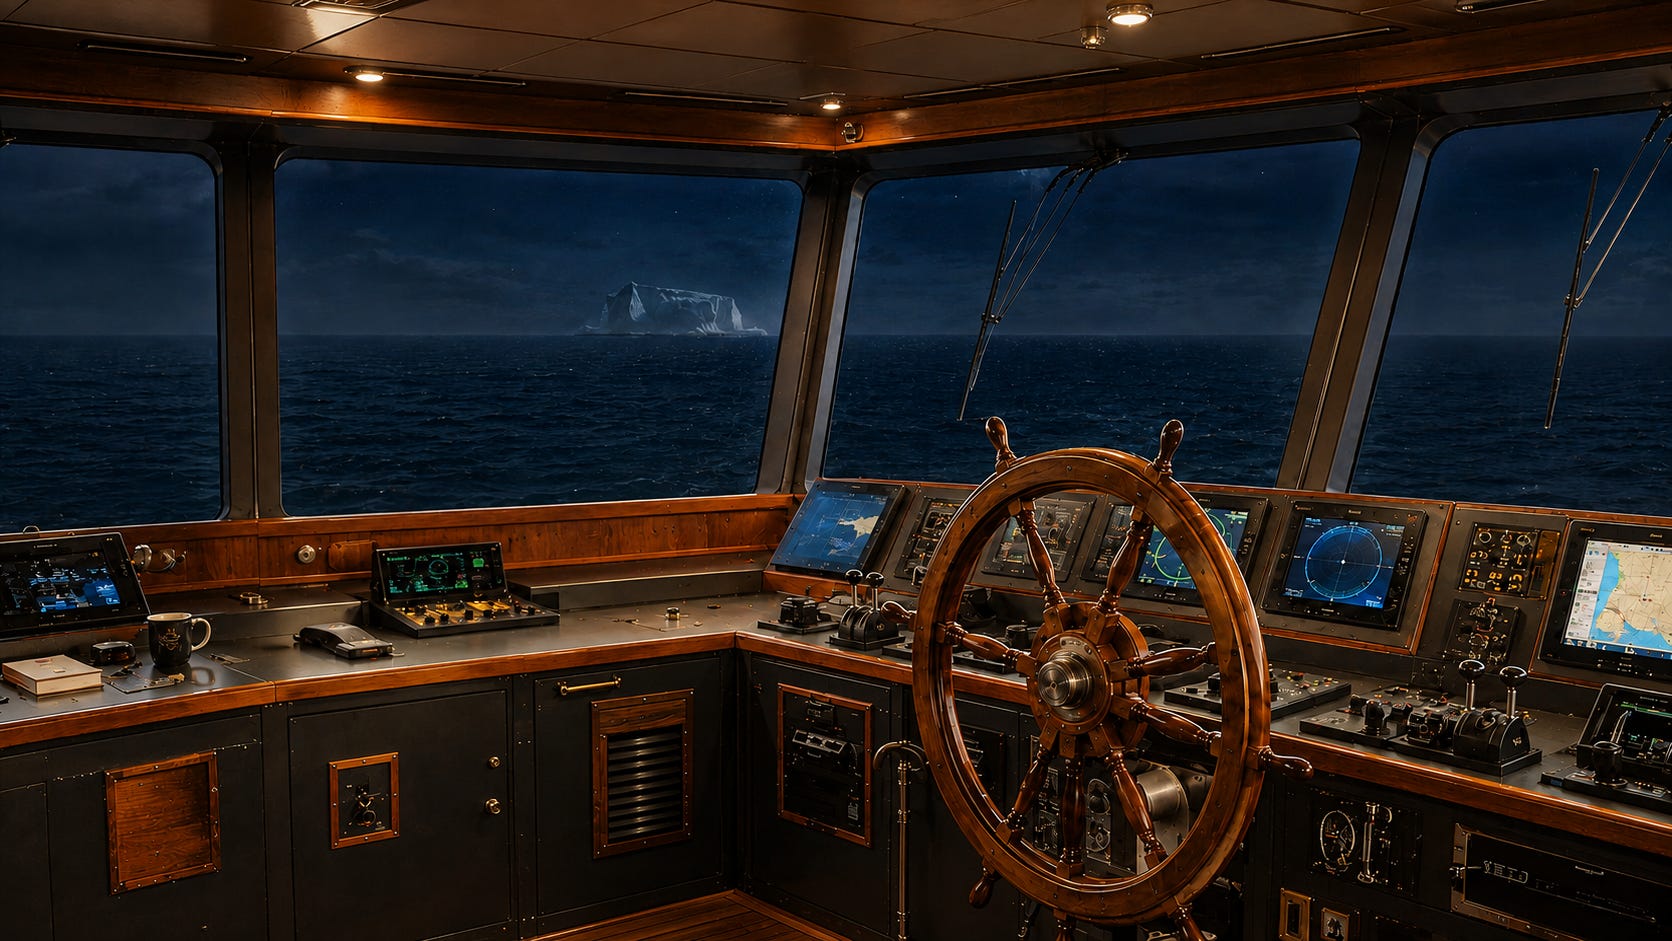
A missing certificate of currency looks like paperwork. It’s actually the difference between a vessel that’s storm-ready and one that only looks it from the dock.
Nobody had been out on deck checking for icebergs. Nobody had been below, running a hand along the hull to see what the weather might find. Not because anyone was careless — because nobody on board had “watch the horizon” as their actual job. The accountant was below decks doing the books. The agent was managing a fleet, not standing at the rail of any one vessel. Everyone was competent, everyone was busy, and not one of them was looking up.
Everyone was doing their own job, but …
The agent’s story was simpler, and no less damning for it.
His system sends renewal reminders automatically, to whichever inbox is on file. Whether this one reached my client or vanished into a spam folder nobody’s opened in a year, nobody can say for certain — and it doesn’t much matter. He’s carrying several thousand policies. He isn’t going to personally chase the ones that don’t renew, because chasing isn’t the job; issuing the reminder is.
The property manager had an equally fair answer. Paying this client’s premium wasn’t something he did — some managers pay a landlord’s insurance out of the rent they collect, as a service; this one didn’t, by arrangement, so a lapsed policy never showed up as a missed payment on his ledger. He may have seen the renewal notice. He may not have. Either way, it wasn’t his to action.
Four professionals. Four reasonable explanations. One uninsured building, for over a year, and not one person whose job it was to ask the only question that mattered: is this still covered?
Sometimes protecting a client’s goals looks like an investment return. Sometimes it looks like a certificate of currency nobody else thought to ask for.
Who’s watching the ship?
The uninsured building was put back under cover. But that’s not really the point of the story.
The point is that four competent people did do their jobs but still missed something that could have ended a family’s financial life.
Not one of them was negligent. It wasn’t a flaw in any of their jobs, either. This exposure arose because something had fallen through the cracks between their jobs. It’s an exposure that sits in a place no accountant, broker, investment adviser or lawyer is actually paid to watch, and the reason why is simple.
You see, from where each of these professionals sat, their view of their part of the ship looked fine. And that’s the point. What could easily have sunk the ship here was that no one had eyes on the whole vessel.
Just whose job is it?
The knee-jerk answer has to be: the Captain of the ship. That ol’ sea dog who the ship has relied on for decades to get in and out of port safely and on time.
But here’s the rub: sooner or later, there comes a time when our Captain realises that – rather than inspecting the hull by candlelight, looking for damage – it’s time to gaze at a flaming pink and red sunset over the rim of a pina colada. Or watch the granddaughter take her first steps. Or listen to the travails of your now-grown children sailing their own ship, with kids of their own.
Does that time ever come? Or is there no one you can trust to do it as well? There’s a lot at stake, you don’t hand the keys to all-comers.
Having someone in your corner, who has your back, can sometimes be about chasing a better return. But it’s always about being on ship’s watch.
Best regards
Daniel Brammall
Two ways I can help:
1) Roadmap Experience (Advisory)
Leave with clearer next steps and a practical path forward.
Book your call → danielbrammall.com/roadmap-experience
2) Retirement Resilience Forecaster (DIY)
See best case, worst case, and what’s more likely, not a straight-line guess.
Get the Forecaster ($27 AUD) → danielbrammall.com/retirement-resilience-forecaster
The WealthSpan Letter is general financial information, not personal financial advice. Consider whether any information is appropriate to your circumstances before acting on it.