

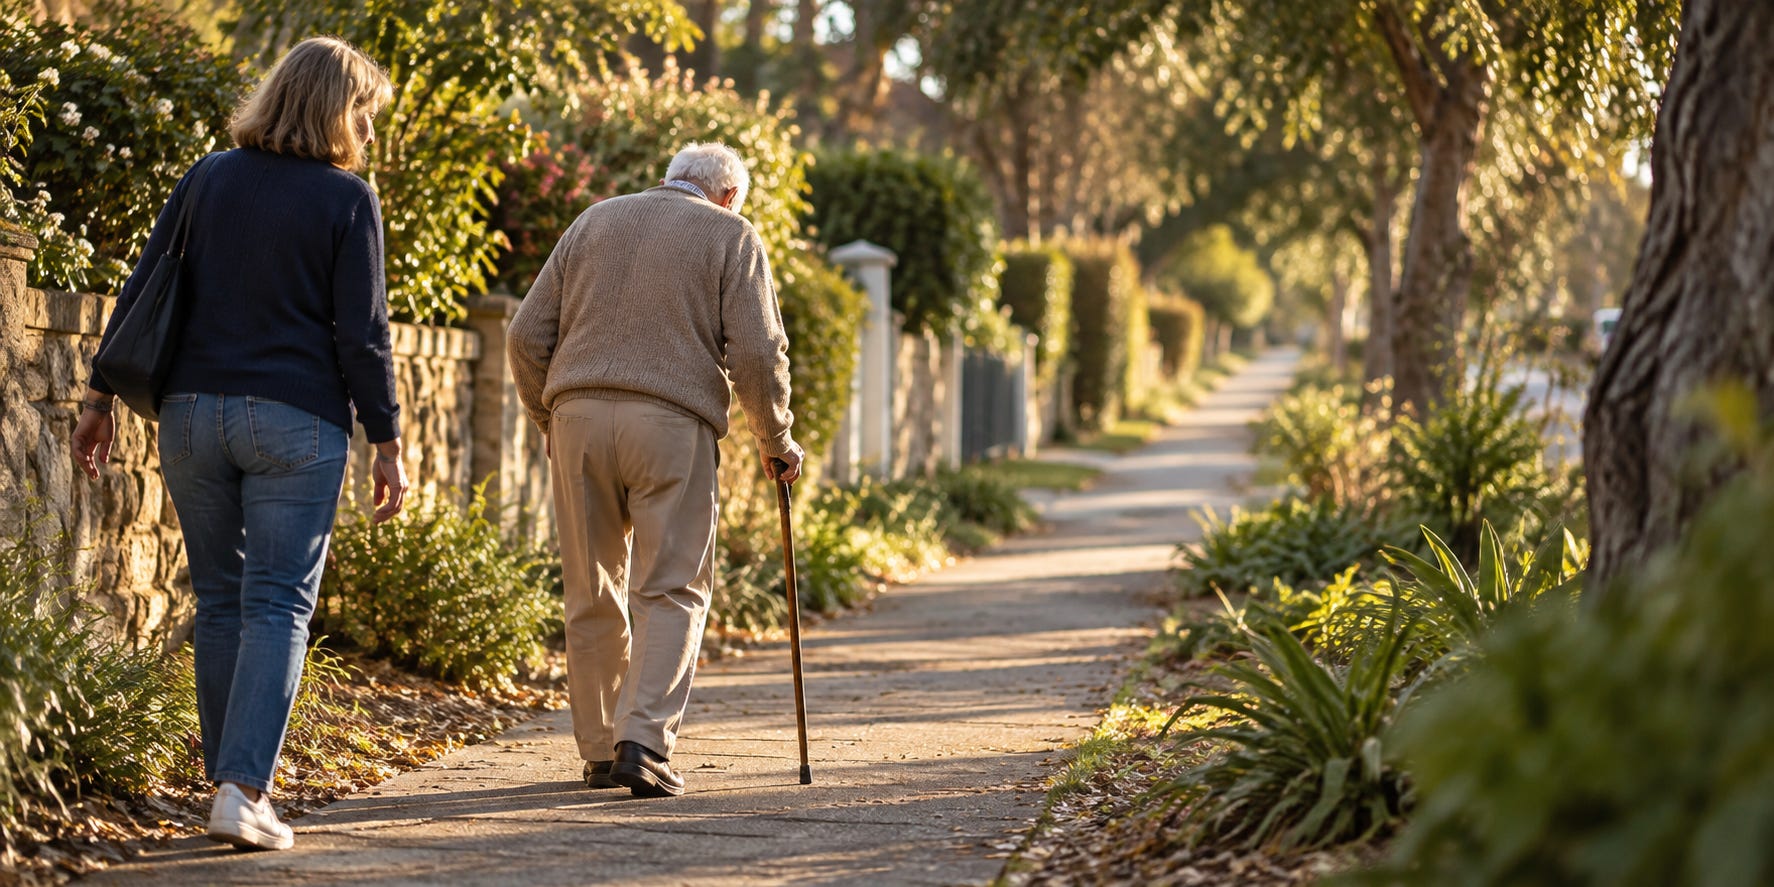
Mum and dad are in their late-eighties now. The last five years have been hard to watch. A few health scares, and somehow they’ve managed to (sort of) dodge each one. They’re not out of the woods and no one’s expecting them to make it out, least of all them.
It isn’t just unpleasant to watch, it’s depressing.
And I suppose – if you’re about my age – you’re having a similar experience (or if not yet, I imagine you will sooner or later).
Talking (as I do) to 50/60-somethings a lot, this conversation seems to come up pretty regularly. They always land in the same place, though. Basically the question is:
Assuming I live that long, is life going to be worth living?
“87?! Ugh, kill me now!”
Sure, it’s funny to read it here, but you’d be surprised how often I hear it. Maybe you wouldn’t?
Either way, here’s the assumption: you’re probably going to live a bit longer than mum and dad, but the last few years is going to be bloody miserable, and so financially speaking, you only need to fund retirement to that age because the dice have already been cast.
But what if you could stack the dice in your favour?
Watching this happen to your folks, you can discount luck, for sure, but putting it all to genetics is short-sighted. The evidence is clear on this: factors largely within your control have a big role to play in just how long and painful your extreme old age is going to be for you.
Yes, this is still a finance piece. What’s the money for, though?
The comedian Jimmy Carr mused recently that there’s not one of us who – in our last year of life – wouldn’t cheerfully exchange all our wealth for the health we enjoyed twenty years earlier.
For me the message is we don’t have to assume our last five years is going to be miserable. We still have choices. And those choices are due now.
Is it all genetics?
Sure, genetics and luck still get a vote.
But as far as the subject of how long – and well – you will live is concerned, people who know lots more than me about longevity point to the evidence. The gap between how long you’ll live and how well you’ll live is measured in double-digit years. We’ll all realise that truth in good time, at the back end of our lives. Actuarially this isn’t a guess.
None of that means a hard ending isn’t sometimes unavoidable. But a long, slow one increasingly looks optional rather than inevitable — and that reframes the whole question. If we can learn anything from watching mum and dad’s experience unfold, it’s that some of this suffering might be within our control.
There is a handful of things within your control that do shift the odds substantially in your favour.
The experiment
I’ve never smoked, never done drugs — more luck than willpower, if I’m honest. Five years ago I gave up alcohol, and it wasn’t the fight I expected. The upside has dwarfed the cost. Seriously.
I bought a ‘wearable’ to get a handle on my sleep, because you can’t fix what you don’t measure. More recently I signed up with one of those online, preventive-medicine clinics — one of a growing number now doing what general practice mostly doesn’t have time for: full biometric workups, not just a chat and a blood pressure cuff.
That’s being unkind.
Standard medical practice saves lives. We’d be buggered without it. But it is symptom-driven. Reactive. What I’m talking about is proactive.
None of it is free, and I don’t mean money (because frankly it’s a helluva lot cheaper than you might think). The real cost is the time, attention, and the kind of follow-through that’s easy to promise yourself on Sunday night and be too busy for by the end of the week.
This is reprioritising – choosing to reinvest time you used to spend on low-payoff endeavours that didn’t really move the needle, into activities that pay off big-time down the road.
For me, making the decision was the biggest needle-mover. It was like a weight lifted off my shoulders immediately.
Although I hadn’t yet done anything to get that cholesterol score down, or my sleep quality score up, the feeling I got was that I’m making an investment that is going to yield a return worth many, many times the effort.
The same discipline, aimed differently
Today I’m about 18 months into that health-tracking program. Progress has been in fits and starts but when I reflect on where I started, I’ve dropped a generous load of fat, and have strapped on a useful portion muscle mass – at my age, very welcome indeed. I won’t bore you with the other health metrics – those are two obvious ones. Suffice it to say that when the doctor confirms I am now 9 years younger, biologically speaking, than my chronological age … I beam.
There’s a parallel here I’ll be careful with, because it’s easy to overstate it. Getting your health organised and getting your money organised call on the same muscle: working out what actually matters, then having the discipline to put it ahead of whatever’s easier or seemingly more urgent in the moment.
Busying myself with stuff is easy as pie. Prioritising the work required to move the metrics requires some consistent follow through. We all know that sleep, nutrition, exercise and mental health are important. Prioritising them isn’t cheap but the evidence says they matter enormously, twenty years on.
This is what Healthspan means in practice
Divide your lifeline into two parts – the working part and the retired part.
If you’re sixty and you’ve done the work, you’re looking down the barrel of another forty years that won’t be spent working — assuming you’ve actually put enough away, which is its own question worth asking. That’s roughly as long as your working life just was.
I’ve started noticing something in the people at exactly this point — throttling back, or making the leap to stop altogether. The ones who seem to be getting it right go after their health with real intent, right about the time they stop going after their career.
Picture a bloke I know: spent three decades building a business, sold it, and within a year had reorganised his whole week around training, sleep, and the numbers his GP used to skim past. He told me the business used to be the metric he tracked. Now it’s this.
I had a conversation just yesterday with another lass retirement planning included buying a stationary bike and a bike training app. She’s got a glint in her eye you can’t miss.
Your money can fund the second life. It can’t live it for you. That part still needs a body capable of doing the things you’re funding — travel, grandchildren, a decent game of golf, or just getting up off the floor without a production number. WealthSpan asks whether the money will last as long as you do. It’s worth asking, just as seriously, whether you will be fit to spend it.
Here’s a good question your financial adviser should be asking: is it possible you’re undervaluing your final years and robbing yourself of a quality of life that’s available but you can’t afford?
Best regards
Daniel Brammall
Two ways I can help:
1) Roadmap Experience (Advisory)
Leave with clearer next steps and a practical path forward.
Book your call → danielbrammall.com/roadmap-experience
2) Retirement Resilience Forecaster (DIY)
See best case, worst case, and what’s more likely, not a straight-line guess.
Get the Forecaster ($27 AUD) → danielbrammall.com/retirement-resilience-forecaster
The WealthSpan Letter is general financial information, not personal financial advice. Consider whether any information is appropriate to your circumstances before acting on it.